Comparing tail variabilities of risks by means of the excess wealth order
Identificadores
URI: http://hdl.handle.net/10498/14974
DOI: 10.1016/j.insmatheco.2009.10.001
URL: http://dx.doi.org/10.1016/j.insmatheco.2009.10.001
ISSN: 0167-6687
Ficheros
Estadísticas
Métricas y Citas
Exportar a



Metadatos
Mostrar el registro completo del ítemAutor/es
Sordo Díaz, Miguel Ángel
Fecha
2009-01-01Fuente
Insurance: Mathematics and Economics 45 (2009), pp. 466-469Resumen
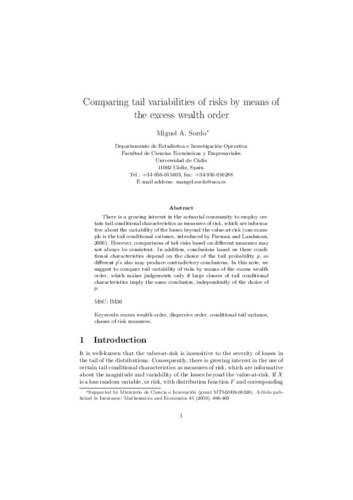
There is a growing interest in the actuarial community to employ certain tail conditional characteristics as measures of risk, which are informative about the variability of the losses beyond the value-at-risk (one example is the tail conditional variance, introduced by Furman and Landsman, 2006). However, comparisons of tail risks based on different measures may not always be consistent. In addition, conclusions based on these conditional
characteristics depend on the choice of the tail probability p, so different p's also may produce contradictory conclusions. In this note, we suggest to compare tail variability of risks by means of the excess wealth order, which makes judgements only if large classes of tail conditional characteristics imply the same conclusion, independently of the choice of p.
Colecciones
- Artículos Científicos [11777]
- Articulos Científicos Est. I.O. [354]

Esta obra está bajo una Licencia Creative Commons Attribution-NonCommercial-NoDerivs 3.0 Unported