Comparison of conditional distributions in portfolios of dependent risks
Identificadores
URI: http://hdl.handle.net/10498/33346
DOI: 10.1016/j.insmatheco.2014.11.008
ISSN: 0167-6687
Estadísticas
Métricas y Citas
Exportar a



Metadatos
Mostrar el registro completo del ítem
Fecha
2015Fuente
Insurance: Mathematics and Economics - 2015, Vol. 61 pp. 62-69Resumen
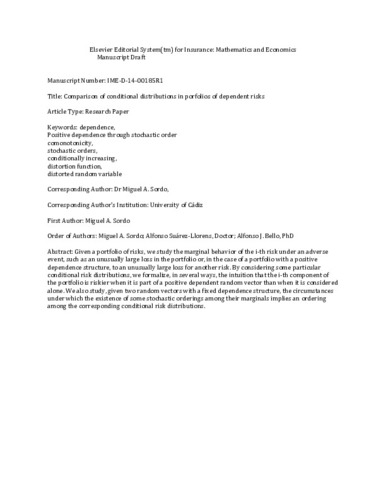
Given a portfolio of risks, we study the marginal behavior of the i-th risk under an adverse event, such as an unusually large loss in the portfolio or, in the case of a portfolio with a positive dependence structure, to an unusually large loss for another risk. By considering some particular conditional risk distributions, we formalize, in several ways, the intuition that the i-th component of the portfolio is riskier when it is part of a positive dependent random vector than when it is considered alone. We also study, given two random vectors with a xed dependence structure, the circumstances under which the existence of some stochastic orderings among their marginals implies an ordering among the corresponding conditional risk distributions.
Colecciones
- Artículos Científicos [11777]
- Articulos Científicos Est. I.O. [354]

Esta obra está bajo una Licencia Creative Commons Attribution-NonCommercial-NoDerivatives 4.0 Internacional